Home loans for self-employed borrowers in Victoria
Self-employed borrowers across Victoria can discuss a residential purchase or refinance with Realloans.
Alongside your income evidence, the property itself matters. An established dwelling, building project, vacant block and improved acreage property raise different assessment questions.
Our confirmed office is at 93 Moxham Drive, Kalkallo VIC 3064. This page helps you identify the property and purpose questions to discuss before an application.

Expert broker at your service
Talk to an expert broker
We review your residential purpose, business circumstances and property information to identify what an application may require.
Comparing lender requirements
Realloans compares relevant options from its lender panel. The lender determines whether the borrower and proposed security meet its requirements.
Application assistance
We can assist with preparing and submitting your application. Approval and timing depend on the lender and the information it requires.
Settlement support
If approved, we can help coordinate the remaining finance requirements through settlement.
Self Employed Home Loan Requirements
Required business history and income documents depend on the lender, business structure and application. The national Self Employed Home Loans guide explains income assessment without a fixed statewide checklist.
Where alternative income evidence needs consideration, see Low Doc Home Loans. Self-employment or a Victorian location does not by itself determine the documentation pathway.
Comparing loan terms
Compare the current costs, repayment terms and conditions of the options available for your circumstances. There is no single product feature set that applies to all Victorian self-employed applications.

First Home Buyer Home Loans
For a first residential purchase, identify the property, your deposit and purchase timing alongside available income evidence. See First Home Buyer Loans for the wider first-purchase discussion. Check any government assistance against current official eligibility requirements before relying on it.
Investor Property Home Loans
For a residential investment, explain the intended use of the property and your existing commitments.
The lender may need property and rental information as well as evidence of your business income. Its requirements and terms depend on the proposed application.
Realloans can assist with the application and comparison of relevant options. It cannot guarantee an approval, particular loan terms or settlement timing.

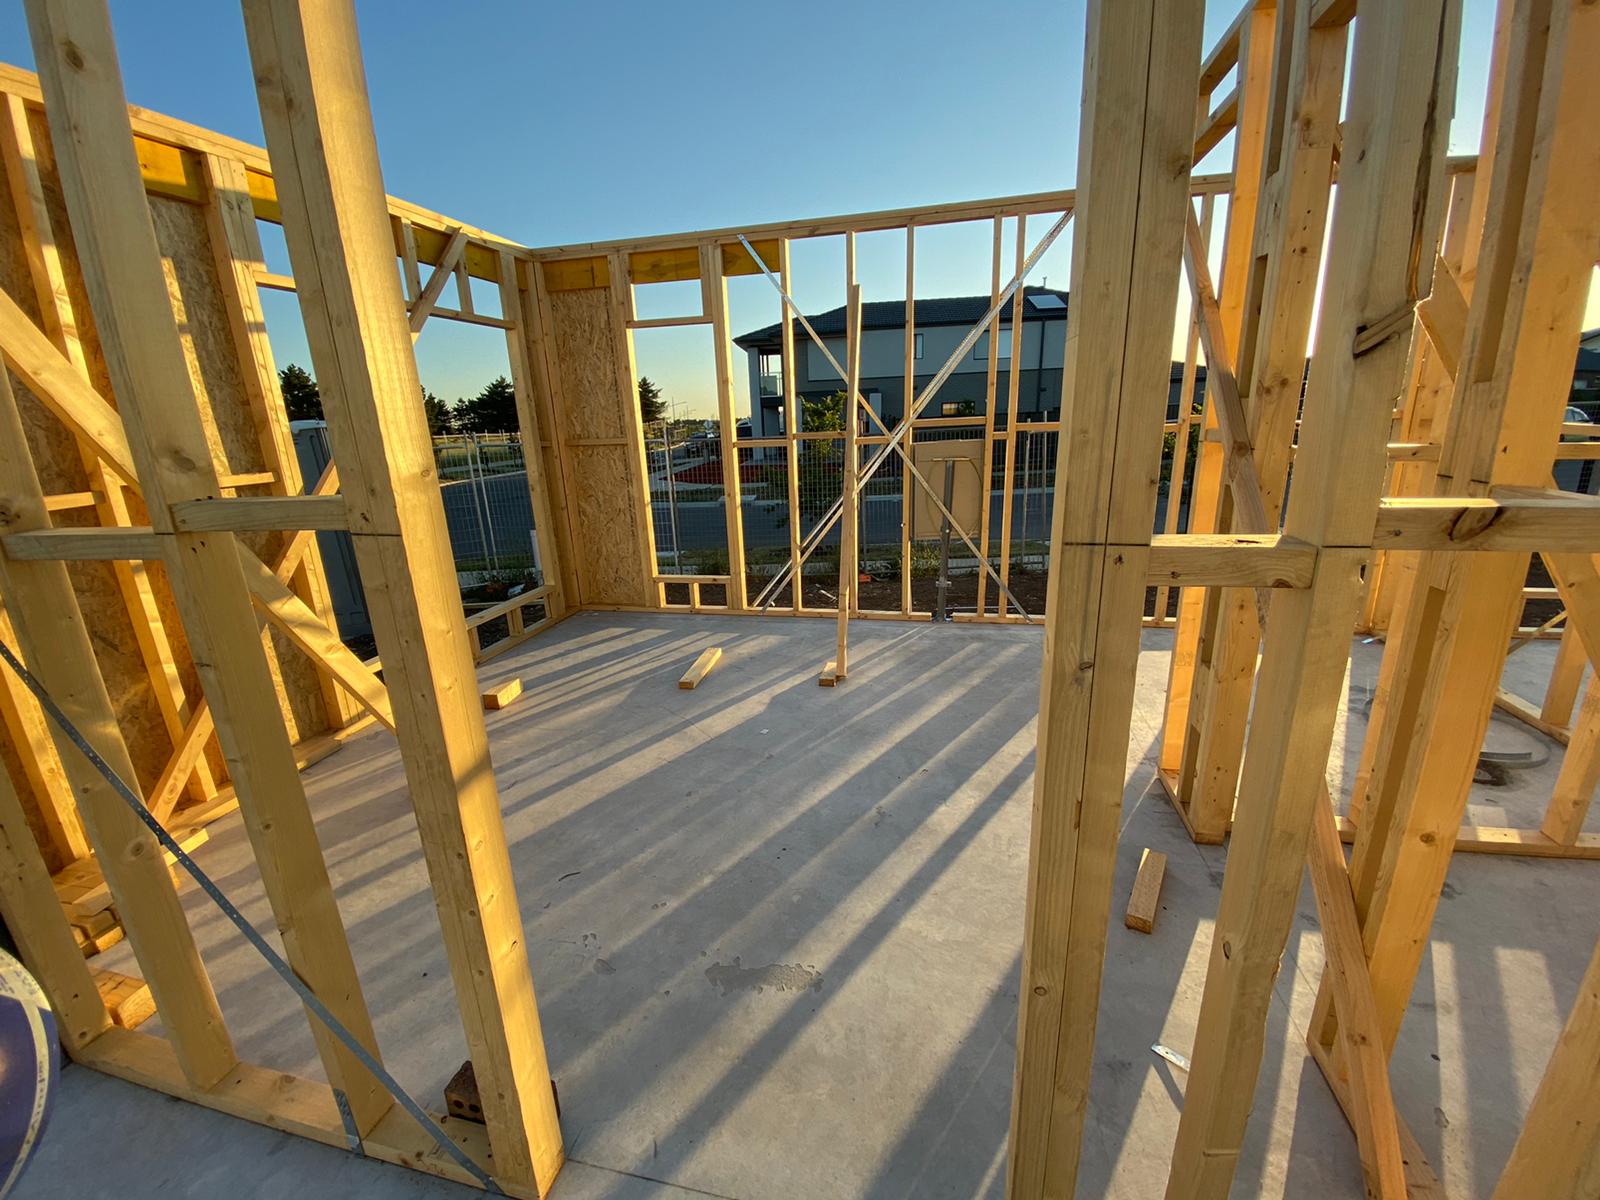
Construction Home Loan for Self Employed
A residential build requires project information alongside your self-employed income evidence. Discuss the available plans, contract and builder information before treating construction as an ordinary established-home purchase. The lender determines the project requirements.
Refinancing Home Loan
Explain the purpose of refinancing your existing residential loan and whether the property use or requested borrowing will change. Review costs and conditions as well as the proposed terms. Equity release or other additional borrowing needs assessment.
Home Loan Pre-approvals
Pre-approval is an indicative and conditional assessment, not final approval for a particular property. A change in the property, business circumstances or application information can require further assessment.
Across Victoria, what changes with the property and purpose?
Established residential property
For an established home, describe the purchase or refinance and the actual property being offered as security. Standard or alternative income evidence depends on your circumstances, not simply on being self-employed.
A residential building project
Construction adds project assessment to the borrower assessment. Use Construction Home Loans for the build process, or Low Doc Construction Loans if alternative income evidence also needs consideration.
A land-only purchase
A vacant block has no established dwelling and needs a land-security discussion. See Vacant Land Loans, or Low Doc Vacant Land Loans where alternative income evidence is also relevant. A future building intention does not make the initial land purchase a construction application.
Improved acreage or rural-style residential property
For a property with an existing dwelling, explain its size, use, improvements and access. Acreage Loans covers that residential security discussion. Agricultural or development purposes require separate consideration.
The actual location and property characteristics
Provide the property address and available details rather than relying on a metropolitan or regional label. The lender decides what security and valuation information it needs. This page does not prescribe postcode-based borrowing limits or regional pricing rules.