Low Doc Construction Loans
Realloans helps self-employed borrowers explore finance for building an owner-occupied home or residential investment property when standard income documents are unavailable.
A low doc construction application brings borrower evidence and building-project information together. Both must meet the proposed lender’s requirements.
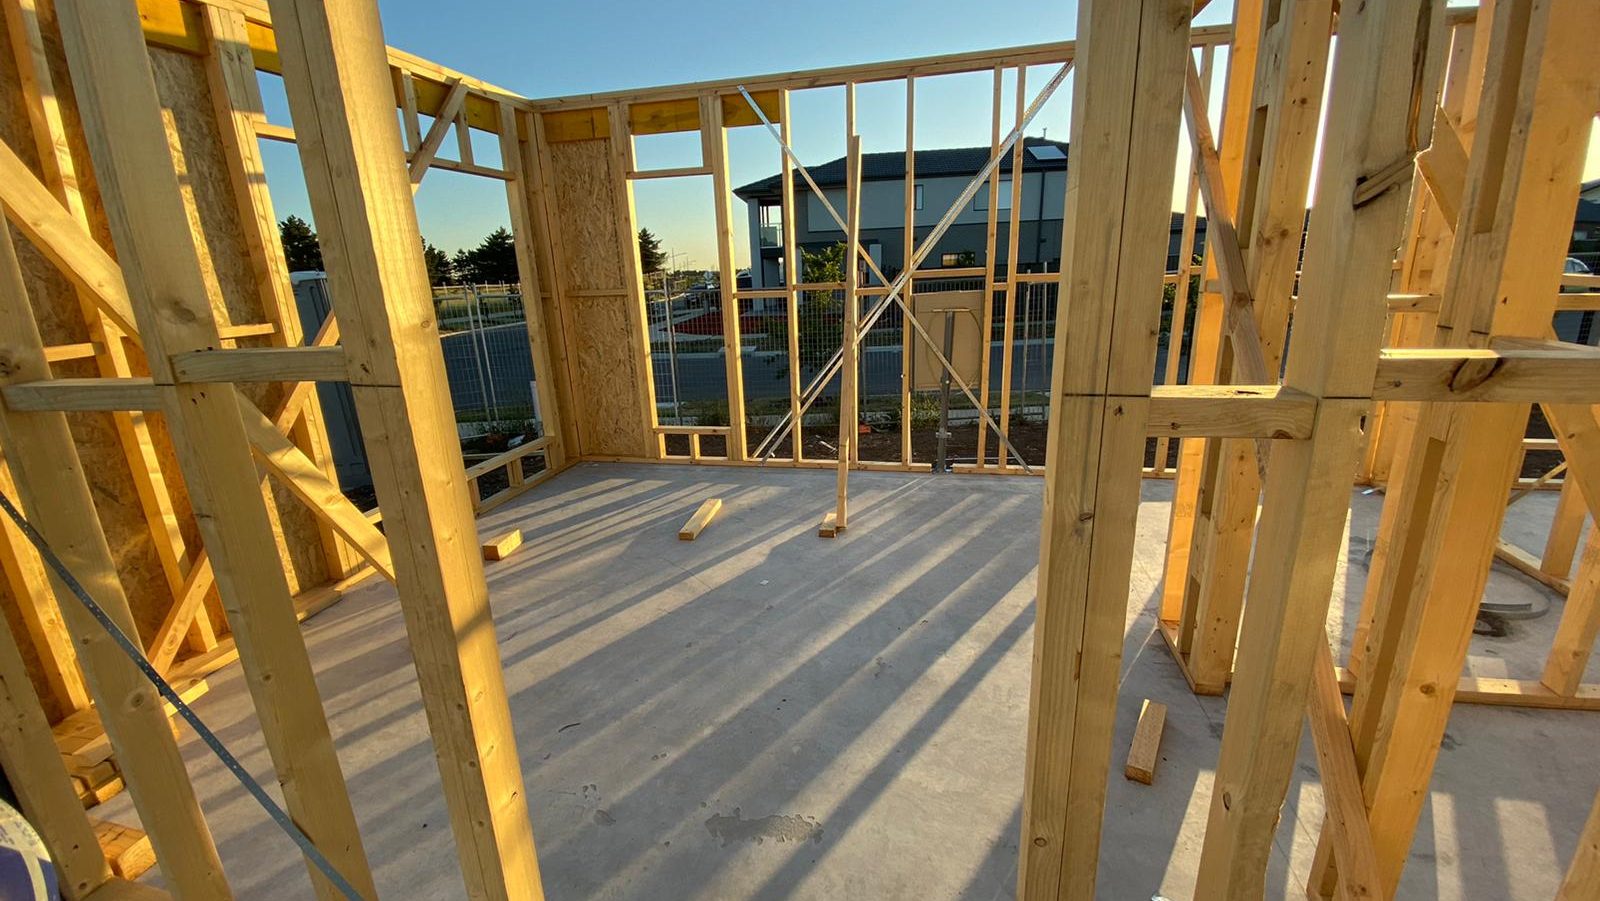
Residential construction considerations
- Individual, company or trust structures, subject to lender requirements
- Loan amount and deposit depend on lender assessment
- Low Doc Home Loans for construction of owner occupied and investment properties
- Proposed property and building costs require lender review
- Credit history is part of application assessment
- Development, subdivision and incomplete projects require separate assessment
Information a lender may request
- Business registration information such as an ABN or ACN
- Alternative income evidence such as BAS, business transaction statements or accountant information, in the combination requested by the lender
- Identity and residency information for lender eligibility checks
- Contract of Sale (if purchase)
- Building contract and price details requested by the lender
- Plans, specifications and relevant approvals
- Building/planning permits
What is a low doc construction loan?
A low doc construction loan combines alternative income evidence with finance for a residential building project. It does not remove the lender’s assessment of your ability to repay or the proposed property.
Construction funds may be released in stages under lender conditions. The lender may require progress evidence, valuations or inspections before payments and completion. See Construction Home Loans for the detailed process.
This page focuses on residential builds. Subdivision and development projects need a separate Development Finance assessment; a stalled or partly completed project may need Incomplete Construction Finance.
Realloans can help coordinate the borrower and project information for lender assessment. If you are only buying land and are not yet building, see Low Doc Vacant Land.
How do I apply for a construction loan?
Start with a general enquiry about your residential build and available income evidence. Realloans can explain requested documents, help prepare and submit the application, and communicate lender requests and decisions.
How much could I borrow for a residential build?
Borrowing capacity depends on your income evidence, commitments, credit position, proposed property, build costs and lender requirements. There is no universal loan amount or loan-to-value limit across low doc construction applications.
Construction Loan with Realloans
Borrower and project review
We review your income-evidence position and residential project before comparing relevant available lender options.
Comparing lender requirements
Lenders can differ in both the alternative income evidence they accept and the construction projects they consider.
Application support
Realloans assists with application preparation and lender communication. The lender determines approval, conditions and release of funds.
When low doc evidence meets a construction application
Borrower evidence
Start with the income evidence you can provide and why standard financials are unavailable. The Low Doc Home Loans guide explains the evidence categories; the proposed lender determines what is acceptable.
Project evidence
The lender also needs information about the residential build. This may include the contract, plans, specifications, builder details, approvals and costs. An acceptable income-evidence pathway does not mean the project is approved.
Both assessments must work together
A lender must be satisfied with the borrower and the proposed construction security. Low doc does not bypass construction assessment, and a build contract does not replace income evidence.
Changes may require more information
Tell your broker about changes to income, business circumstances, contract terms or build costs. The lender may require updated evidence or reassessment before proceeding.
The lender controls drawdowns
Realloans can assist with documents and communication. Approval conditions, progress checks and release of construction funds remain lender decisions.