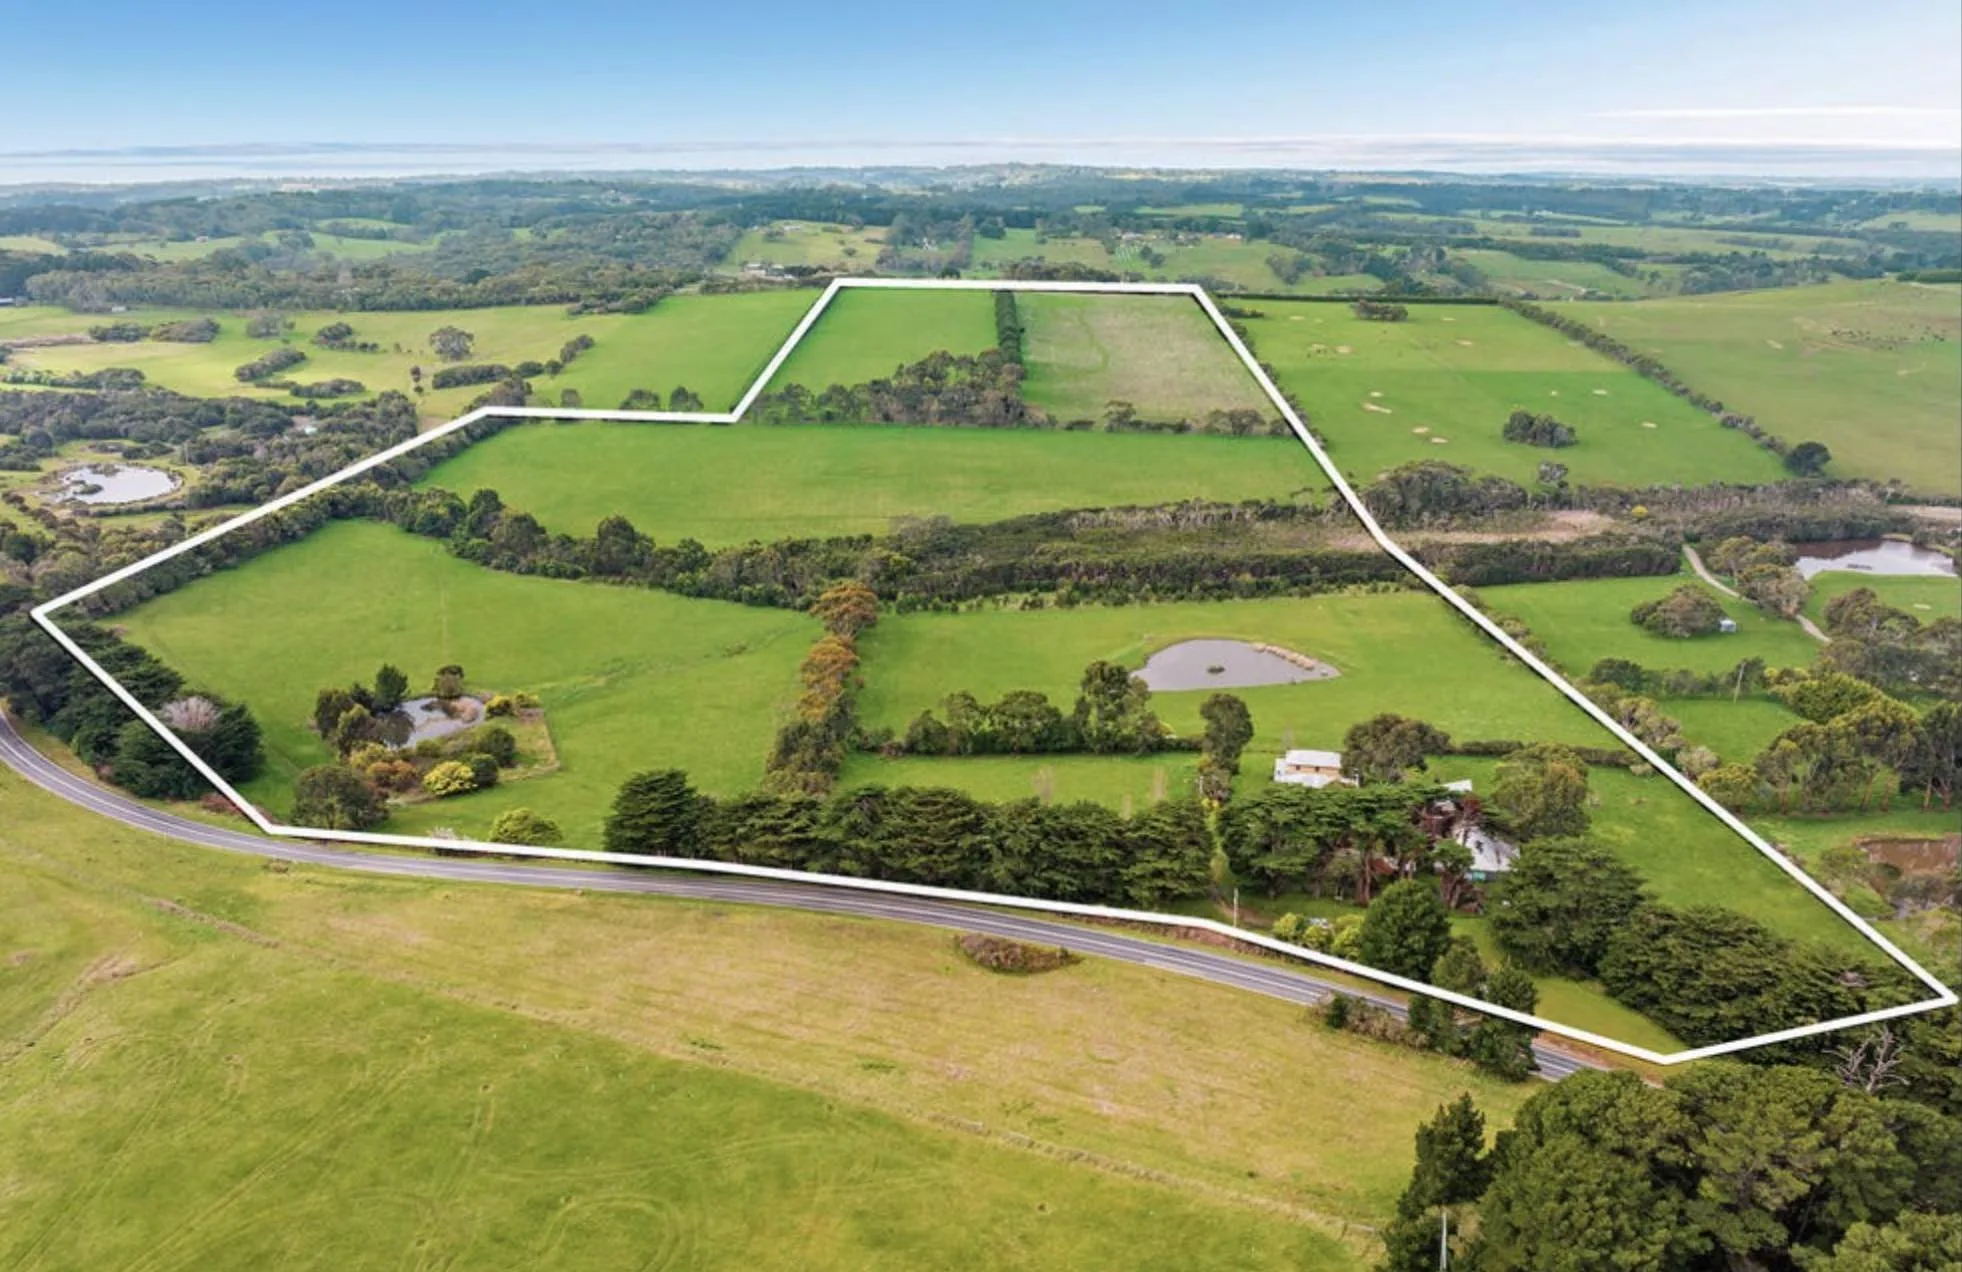
Acreage Loans in Australia
Realloans helps borrowers compare finance to purchase or refinance residential acreage and lifestyle properties in Australia.
This page focuses on rural-style residential property with an established dwelling. Vacant acreage and property used mainly for agricultural or commercial activity may require a different lender assessment or finance structure.
enquire nowHow Realloans Helps with Residential Acreage Finance
Property and Finance Review
We review the dwelling, land characteristics, location, access, services, primary use and borrower position before comparing available lender options.
Lender Comparison
As a finance broker, Realloans can compare relevant lenders whose residential-security criteria may accommodate the assessed acreage property. Availability and suitability depend on lender policy and the application.
Acreage Loan Application Support
We help organise the application and explain lender requests. The lender decides whether it will accept the property as security and determines approval, conditions, valuation requirements and timing.
Settlement Support
We can follow up information requests and keep you updated through assessment and settlement. The lender and transaction parties control approval and settlement timing.
What is a residential acreage loan?
A residential acreage loan may finance a home on a larger or rural-style parcel where the dwelling, land size, location, access, services, zoning or use needs additional lender consideration compared with a standard suburban property. Lender classification varies.
How Lenders May Assess a Residential Acreage Property
- Is there an established residential dwelling? The type and condition of the home matter alongside the land. Lenders assess the whole improved property, not just its acreage.
- What is the primary use? Residential or lifestyle use is the focus here. Limited hobby activity needs lender-specific review; material agricultural or business use may require a different finance structure.
- What makes the land unusual? Size, zoning, topography and other features may affect valuation and lender appetite. There is no universal hectare cutoff that determines approval or the required contribution.
- How accessible and usable is the property? Location, road access and the local residential market may affect whether a lender accepts the security and how readily the whole property could be sold.
- What services and improvements are included? The dwelling, services, sheds, outbuildings and other improvements are considered together. Provide property details so the lender can identify any further information it needs.
- Is this residential acreage, vacant land or a commercial property? An established home used mainly for residential or lifestyle purposes is different from an unimproved block or an income-producing agricultural operation. Confirm the property use before selecting a finance pathway.
Acreage Loan Features
| Core property type | Improved residential or lifestyle acreage with an established dwelling |
| Loan purpose | Purchase or refinance, subject to lender criteria |
| Property assessment | May include the dwelling, land characteristics, location, access, services, improvements, zoning, use and valuation |
| Borrower assessment | May include income, expenses, liabilities, credit history, contribution or equity and supporting documents |
| Loan structure | Available amounts, pricing, repayment types and features vary by lender, security and application |
Which lenders may offer residential acreage finance?
Realloans can compare available residential-acreage products from banks, non-bank lenders and specialist lenders. Documentation methods, repayment types and features vary by lender, property and borrower circumstances.
Not every lender accepts every acreage property. The dwelling, land, location, use, valuation and borrower circumstances determine which options may be available.
The borrower contribution and lending limit depend on lender policy, valuation, property classification, location, use and serviceability.

Acreage interest rates
Residential acreage pricing is not one standard rate. It depends on the lender, property, valuation, loan structure and borrower position.
Lenders may assess the marketability of the whole improved property, including its dwelling, land, access, services, use and location. Realloans can compare the pricing and conditions available for the assessed application.
Acreage Loan FAQs
What is a residential acreage loan?
It is finance for a home on a larger or rural-style parcel where the dwelling, land, location, access, services, zoning or use may require additional lender assessment. Lender classification varies.
How do lenders assess an acreage property?
A lender may assess the dwelling, land size and characteristics, location, access, services, improvements, zoning, primary use, valuation and marketability together with the borrower position.
Can I refinance a residential acreage property?
Refinancing may be possible where a lender accepts the property as residential security. The lender will assess the current property, valuation, loan purpose, borrower position and requested loan structure.
What if the property includes hobby-farm activity?
Limited hobby activity may still require lender-specific assessment. If the property is principally an income-producing agricultural or commercial operation, a residential home-loan structure may not be appropriate.
What if I am self-employed?
Self-employed borrowers may have different income-evidence options. See our Low Doc Home Loans page where standard income documents are not available. Eligibility and evidence requirements depend on the lender.
What information may a lender require?
A lender may request identification, income and liability information, the contract of sale, property details, valuation information and evidence about the dwelling, access, services, improvements, zoning or use. Requirements vary by lender and property.
Other property and income pathways
- Vacant Land Loans: for a block without an established dwelling.
- Construction Home Loans: when the land is secured and you are moving to build finance.
- Low Doc Home Loans: where self-employed income needs a different evidence pathway, subject to lender requirements.
If the property is primarily used for agriculture or business, discuss its use with Realloans before proceeding with a residential application. A separate assessment may be needed; a commercial outcome is not guaranteed.